Rate and Sean Goudreau have no affiliation with any government agency.
VA home loans, made simple.
You earned a benefit that lets you buy with nothing down and no mortgage insurance. Here is what it actually costs, explained by someone who closes these loans every week.
Sean Goudreau·NMLS #326155·Rate
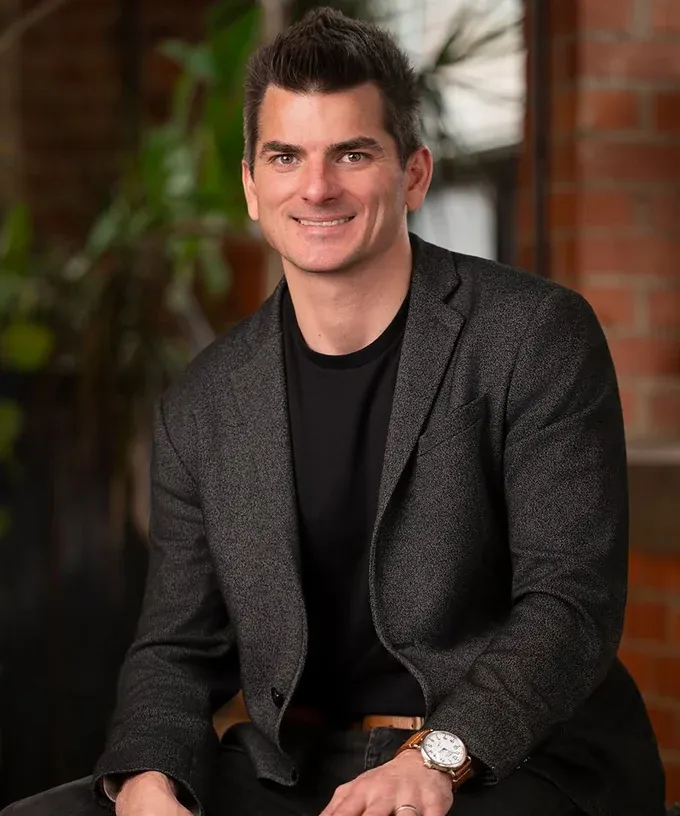
Who you are actually talking to
I am Sean Goudreau. I have spent my career in residential mortgages, and VA loans are the part of the job I care most about getting right, because the people using them have the least room for a lender who guesses.
Most of what goes wrong on a VA loan goes wrong early, before anyone is under contract. A buyer runs a generic calculator that adds mortgage insurance they will never pay. A veteran with a 10% disability rating never mentions it and pays a funding fee they were exempt from. Someone assumes a county loan limit applies to them when it does not. None of that is complicated. It just takes someone who works these loans often enough to ask the right question first.
More than just zero down
You never pay mortgage insurance
Conventional loans under 20% down and every FHA loan carry monthly mortgage insurance. VA loans do not, ever. That difference compounds every month you hold the loan, and it is the single largest reason a VA payment beats other loan programs.
The benefit is not one time
You can use a VA loan, sell, and use it again. In some cases you can carry two VA loans at once on remaining entitlement, which is what makes it work for a family that moves on orders and wants to keep the first house.
Your loan can be assumed
A qualified buyer can take over your VA loan at its original rate when you sell. In a market where rates have risen since you closed, that turns your mortgage into something you are selling alongside the house.
Estimate your VA loan payment
A generic mortgage calculator will get a VA payment wrong in two different ways. It adds mortgage insurance you will never pay, and it leaves out the funding fee most borrowers finance into the loan. This one handles both.
Funding fee $0
Important information about this calculator
The calculator on this page is provided for illustrative and educational purposes only. All examples are hypothetical and are for illustrative purposes only. This information is not intended to be an offer or a solicitation of an offer for a loan.
The calculations made by this tool are based on the information you input and on the assumption that the interest rate does not change during the loan term. Results may vary based on lender guidelines, market conditions, and individual financial circumstances.
Actual loan terms, payment amounts, and interest rates will be determined based on your credit history, income, assets, property value, and other factors. Monthly payment examples do not include amounts for taxes and insurance premiums, and actual payment obligations may be greater.
VA loans require a VA funding fee which varies based on down payment percentage, whether you've used your VA loan benefit before, and your military category. Veterans with service-connected disabilities may be exempt from the funding fee.
Also: the VA funding fee · BAH buying power
Frequently Asked Questions
What is a VA home loan?
A VA home loan is a mortgage backed by the Department of Veterans Affairs for eligible veterans, service members and some surviving spouses. It requires no down payment for borrowers with full entitlement and charges no mortgage insurance. Instead it carries a one-time funding fee of 0.5% to 3.3%, which many veterans are exempt from paying.
Who qualifies for a VA loan?
Eligibility comes from service history. Most veterans, active duty service members, National Guard and Reserve members with qualifying service, and some surviving spouses qualify. You prove it with a Certificate of Eligibility, which your lender can usually pull in minutes.
Eligibility is separate from approval. The VA says you can use the benefit. The lender decides whether the loan works based on credit, income and the property.
Do I need a down payment?
No, not with full entitlement. That is the core of the benefit. Putting money down is optional, and it does lower the funding fee at the 5% and 10% thresholds, so it is worth modeling both ways rather than assuming zero down is always cheapest over thirty years.
Can I use a VA loan more than once?
Yes. The benefit is not one-time. You can reuse it after selling and paying off a prior VA loan, and in some cases you can hold two VA loans at once using remaining entitlement. Subsequent use raises the funding fee on a zero-down purchase from 2.15% to 3.3%, though putting 5% or more down erases that difference entirely.
Latest from the VA Loan Guide
Can Someone Assume Your VA Loan? What It Costs You
A VA loan can be assumed at its original rate, which is valuable when rates are high. But an assumption can tie up your VA entitlement for years. ...more
VA Loan Guide
September 07, 2026•6 min read
Are There VA Loan Limits in 2026? What Actually Applies
VA loan limits were removed in 2020 for borrowers with full entitlement. Here is the 2026 figure, who it still applies to, and why the old rule persists. ...more
VA Loan Guide
September 04, 2026•6 min read
Why Do Sellers Reject VA Loan Offers? What Actually Works
Sellers turn down VA offers over closing speed, appraisals and zero down. Here is what is actually true and how to get a VA offer accepted. ...more
VA Loan Guide
September 01, 2026•7 min read
Ready for a real number?
An estimate gets you oriented. A pre-approval gets your offer accepted. It takes about fifteen minutes.
No credit pull or application. Sean will reach out personally.
Sean Goudreau
Mortgage Loan Officer
NMLS #326155
Rate
465 Waverley Oaks Rd Ste 200
Waltham, MA 02452
VA Loans
Refinance
Tools
Company
Rate is a private corporation organized under the laws of the State of Delaware. It has no affiliation with the US Department of Housing and Urban Development, the US Department of Veterans Affairs, the Nevada Department of Veterans Services, the US Department of Agriculture, or any other government agency. No compensation can be received for advising or assisting another person with a matter relating to veterans’ benefits except as authorized under Title 38 of the United States Code.
Applicant subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not represent an approval for financing or interest rate guarantee. Refinancing your mortgage may increase costs over the term of your loan. Restrictions may apply.
All information provided in this publication is for informational and educational purposes only, and in no way is any of the content contained herein to be construed as financial, investment, or legal advice or instruction. Rate does not guarantee the quality, accuracy, completeness or timelines of the information in this publication. While efforts are made to verify the information provided, the information should not be assumed to be error-free. Some information in the publication may have been provided by third parties and has not necessarily been verified by Rate. Rate, its affiliates, and subsidiaries do not assume any liability for the information contained herein, be it direct, indirect, consequential, special, or exemplary, or other damages whatsoever and howsoever caused, arising out of or in connection with the use of this publication or in reliance on the information, including any personal or pecuniary loss, whether the action is in contract, tort (including negligence) or other tortious action.
This site is not authorized by the New York State Department of Financial Services. No mortgage loan applications for properties located in New York will be accepted through this site.
Operating as Guaranteed Rate, Inc. in New York.
Guaranteed Rate, Inc. D/B/A Rate; NMLS #2611; Rate.com; 3940 N Ravenswood, Chicago, IL 60613; 866-934-7283. For licensing information visit nmlsconsumeraccess.org. Equal Housing Lender. Conditions may apply. • GA: Residential Mortgage Licensee #20973 • MA: Mortgage Lender & Mortgage Broker License #MC2611 • ME: Supervised Lender License #SLM11302 • NH: Licensed by the New Hampshire Banking Department, Lic #13931-MB • NJ: Licensed by the N.J. Department of Banking and Insurance • NY: Licensed Mortgage Banker - NYS Department of Financial Services, 750 Lexington Ave. Suite 2010, New York, New York 10022 • OH: MB 804160 • RI: Rhode Island Licensed Lender
© Copyright Make Your VA Loan Simple and Sean Goudreau 2026. All rights reserved. Privacy Policy. Terms of Use. Sitemap.